Audit Services in Malta
Your annual statutory audit, a change of auditor or outstanding audit years. Tell us your company and the periods involved; we explain the records needed and agree the scope and fees before work begins.
Request Your ConsultationFree consultation. No obligations.
- Auditing and Accountancy warrant held since 2017
- Founder oversight of audit work
- Free initial consultation
- Fees agreed in a written proposal
- A reply within one business day
Led by
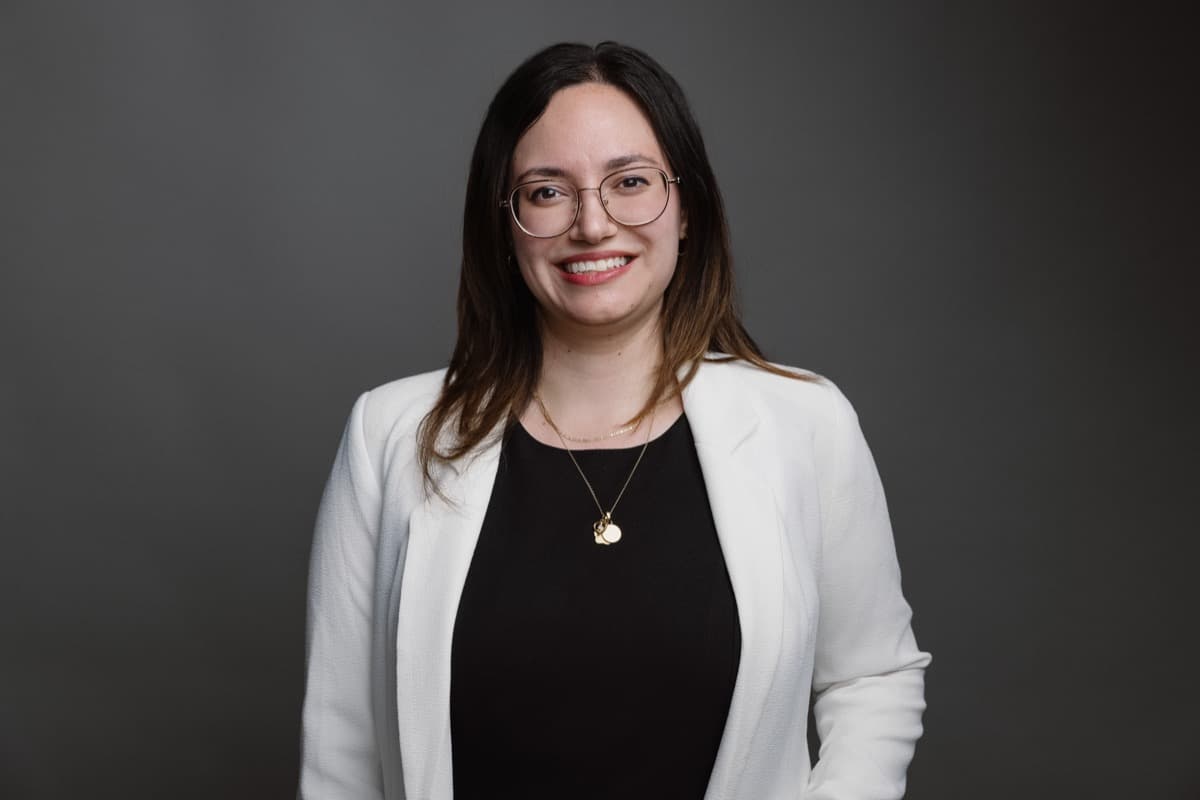
Tatiana Muscat
Audit Manager
Start with the audit matter you need to address
For your annual statutory audit, tell us the financial year-end, how far the accounts have progressed and any reporting deadline. We discuss the requirement for your company and the records needed before proposing an engagement.
If you are changing auditor, explain which year is complete and what remains in progress. For outstanding audit years, list the periods involved and any missing records. These details help us discuss the proposed handover or the work needed to catch up.
The first consultation is free and without obligation. Scope and fees for subsequent work are agreed in a personalised written proposal. Accounts preparation, audit work and any filing support are distinguished in the agreed scope.
Our Audit Services
Discuss the annual audit of your company's financial statements and the requirement for the relevant year. If you are unsure whether an audit is required, we assess the position for your company before proposing the engagement.
The work involves planning, examining supporting evidence and reporting an independent audit opinion. Any accounts preparation, tax return work or filing support is identified separately in the agreed scope.
An audit examines financial statements and supporting evidence under the applicable reporting framework. Tell us whether draft accounts are available and whether the enquiry concerns the current audit period or earlier years.
We explain the information needed and raise questions with your team during the work. The audit opinion depends on the evidence obtained.
For a larger company, start with the business activities, reporting framework, locations and financial year concerned. Explain any group reporting requirement or deadline.
We discuss the proposed scope, the records available and coordination with your finance team before agreeing the engagement.
For a holding company audit, tell us what the company holds, its place in the group and the financial year involved. Investment records, financing arrangements and related-party information help establish the work required.
We discuss the relevant reporting framework and any group reporting needs as part of scoping.
A group audit concerns consolidated financial statements. Tell us which entities are involved, where they operate and how far the consolidation and individual company accounts have progressed.
We discuss reporting requirements, supporting information and coordination with the people responsible for each entity before agreeing the scope.
International Financial Reporting Standards (IFRS) provide a framework for preparing financial statements. Tell us if your company already reports under IFRS or needs to establish which framework applies.
We discuss the audit of those financial statements and the evidence required. Any accounting preparation or implementation support is identified separately in the proposal.
The General Accounting Principles for Small and Medium-Sized Entities (GAPSME) are a financial reporting framework used in Malta. Suitability depends on the company's circumstances.
Tell us which framework your accounts use and which financial years need auditing. We discuss the applicable reporting requirements and distinguish preparation work from the audit engagement.
How we work with your company
Borg Galea combines personal attention with founder oversight. Nathaniel Borg leads audit. You receive a proposed scope and fees before deciding whether to proceed.
Warranted audit work
The Auditing and Accountancy warrant has been held since 2017. We discuss the engagement appropriate to your company and reporting needs.
Founder oversight
Nathaniel Borg leads the audit department, with senior oversight of the work and a dedicated team that knows your business.
A reply within one business day
We reply to your questions within one business day. Audit timing is discussed separately after reviewing the scope and records available.
Scope and fees agreed in advance
Your personalised written proposal explains the work and fees. Any accounts preparation or additional support is distinguished from the audit engagement.
From initial conversation to audit report
“Begin with your company, the financial years concerned and the reason for your enquiry. We explain the next steps and the information needed.”
01
Initial consultation and proposal
The first conversation is free and without obligation. We discuss the company, the audit requirement and any deadline or change of auditor.
Tell us whether the enquiry concerns an annual audit, an auditor change or outstanding years. We consider the records available and identify any preparation work needed. Scope and fees are agreed in a personalised written proposal before work begins.
Planning and records
We establish the reporting requirements and explain which documents your team needs to prepare.
Depending on the engagement, records may include draft financial statements, a trial balance, ledgers, bank statements, invoices and agreements. Prior-year audited accounts and group or related-party information may also be needed. Tell us if records are incomplete or held by another advisor.
Audit work and questions
We examine the financial statements and supporting evidence and follow up questions with your team.
The procedures reflect the company and the areas being audited. We discuss findings with management and identify further evidence needed. The timetable depends on the scope, records and responses to audit questions.
Reporting
The audit opinion reflects the work performed and the evidence obtained.
We discuss the reporting process and any separately agreed filing support. An unmodified audit opinion is not guaranteed. Any subsequent support or follow-up work is addressed through the agreed engagement scope.
Discuss your annual audit, auditor change or outstanding years
Request Your ConsultationQuestions before your audit enquiry
The requirement depends on the company and the relevant financial period. Tell us the entity, activities and year concerned, together with any lender or group reporting requirement. Any exemption needs to be assessed for those circumstances.
Tell us which year your current auditor has completed and what remains open. We discuss the proposed appointment, handover and information needed before accepting an engagement.
Yes. List the years concerned and how far the accounts have progressed for each. We assess the records available and discuss preparation work, audit scope and timing.
For the initial enquiry, provide your company, the year or years and a short description of the need. For the audit itself, records may include draft accounts, trial balances, ledgers, bank statements, invoices, agreements and prior-year audited financial statements. We explain the requirements for your engagement.
Tell us what is available and what is still missing. Accounts preparation is distinguished from the audit, so you can understand the work that needs to happen before or alongside the engagement.
Timing depends on the company, the years involved, the records available and the work required. Include any reporting deadline in your enquiry so we can discuss it when assessing the proposed engagement.
Following the free initial consultation and scoping, pricing is agreed in advance in a personalised written proposal. The proposal identifies the agreed work and fees before you proceed.
We discuss findings with management and request further evidence where needed. The audit opinion reflects the evidence obtained; a particular opinion cannot be promised in advance.
Related Publications
Stay informed with our latest insights and expert guidance.
Audit & Assurance
The importance of a Letter of Engagement for an Auditing firm Introduction
What is the letter of engagement? The engagement letter is one of the most fundamental elements within an audit engagement. It is in fact, the first step which every audit must start from. In basic terms, this is the written document which both the client and the audit firm conform to, and it outlin
Audit & Assurance
Audit Confirmation Letters: Everything You Need to Know
The Use of Confirmation Letters During the course of an audit, auditors are required to obtain sufficient audit evidence on the basis of which to establish their opinion. Confirmation letters are considered to be among the most persuasive forms of audit evidence because they are received directly fr
Request Your Audit Consultation
Tell us your company, the year or years involved and your reason for enquiring. If the period is unclear, say so. The initial consultation is free and we reply within one business day.
You will speak with
Andrew Fenech
Business Development Manager
Tatiana Muscat
Audit Manager
- Free initial consultation
- A reply within one business day
- No obligations whatsoever