Corporate Tax in Malta How the 35% rate and the shareholder refund work for your company.
A Malta company pays 35% tax on chargeable income, and shareholders can generally claim back 6/7 of the tax on distributed trading profits, bringing the overall tax to 5%. Tell us how your company is set up and we explain how this applies to you.
ACCA-qualified staffTax, accounting and audit through one relationship

You will speak with Andrew Fenech
- Participation exemption for qualifying holding company income
- Tax account allocation and refund claims
- Pricing agreed in advance, with no hidden charges
“I have been a client of Borg Galea & Associates for 5 years and have always found their services to be extremely professional and approachable. They support me through many financial tasks, both on a personal level and in respect of my company. They also enlist the help of other professionals to ensure that informed decisions are made. I highly recommend their services.”
 Daniel CutajarDino’s Motors
Why Borg Galea
Direct communication with decision-makers
Complex questions reach the people who can decide.
One relationship. Everything handled.
Tax, accounting and audit, with all services under one roof.
A local team in Birkirkara
The team works from our office in Birkirkara, at Centris Business Gateway.
Scope and fees agreed in writing
Pricing is agreed in advance in a personalised written proposal, with no hidden charges.
- Borg Galea is a member of FinanceMalta, IFSP, MIA, MIT and MEA.
Malta corporate tax at a glance
The company pays 35%. The refund to shareholders depends on the type of income.
| Income type | Shareholder refund | Overall tax after refund |
|---|---|---|
| Trading income | 6/7 | 5% |
| Passive interest and royalties | 5/7 | 10% |
| Dividends and gains from a participating holding | Participation exemption | 0% |
Refunds are claimed by the shareholders after a dividend is paid and are not paid to the company. The participation exemption applies only where the holding and the income meet the conditions of the Income Tax Act.
Which corporate tax matter do you need to address?
- 01
Choosing the structure
We assess whether a trading company, a holding company or a two-tier structure fits your business and your shareholders.
- 02
Refund claims
We prepare and submit shareholder refund claims and handle the correspondence with the tax authorities.
- 03
Ongoing compliance
Company tax returns, substance documentation and the anti-avoidance rules that apply to your structure.
- 04
International coordination
For cross-border groups, we work with your advisors abroad so the Malta structure fits the wider tax picture, including Pillar Two.
From first conversation to tax proposal
- 1
Discuss your company and shareholders
A free, no-obligation consultation about your business, your shareholders and your plans.
- 2
Review the tax position
We review how Malta corporate tax, refunds and exemptions apply, and explain the options.
- 3
Agree the written proposal
You receive a personalised written proposal with scope and fees agreed before work begins.
Who you will work with
Christine Ann Galea leads direct tax. Co-founder Nathaniel Borg oversees the tax department and international tax matters. Complex questions reach the people who can decide. The team works from our office in Birkirkara.
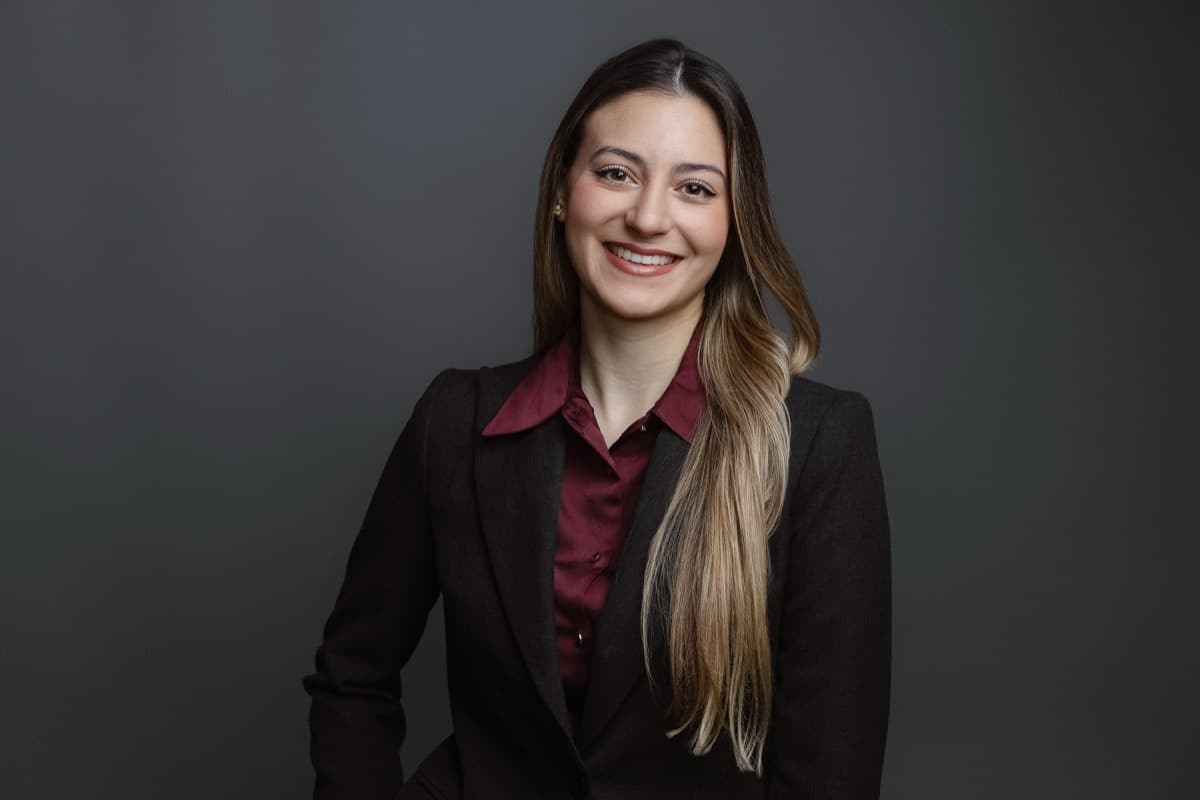
Christine Ann Galea
Tax Transformation Leader
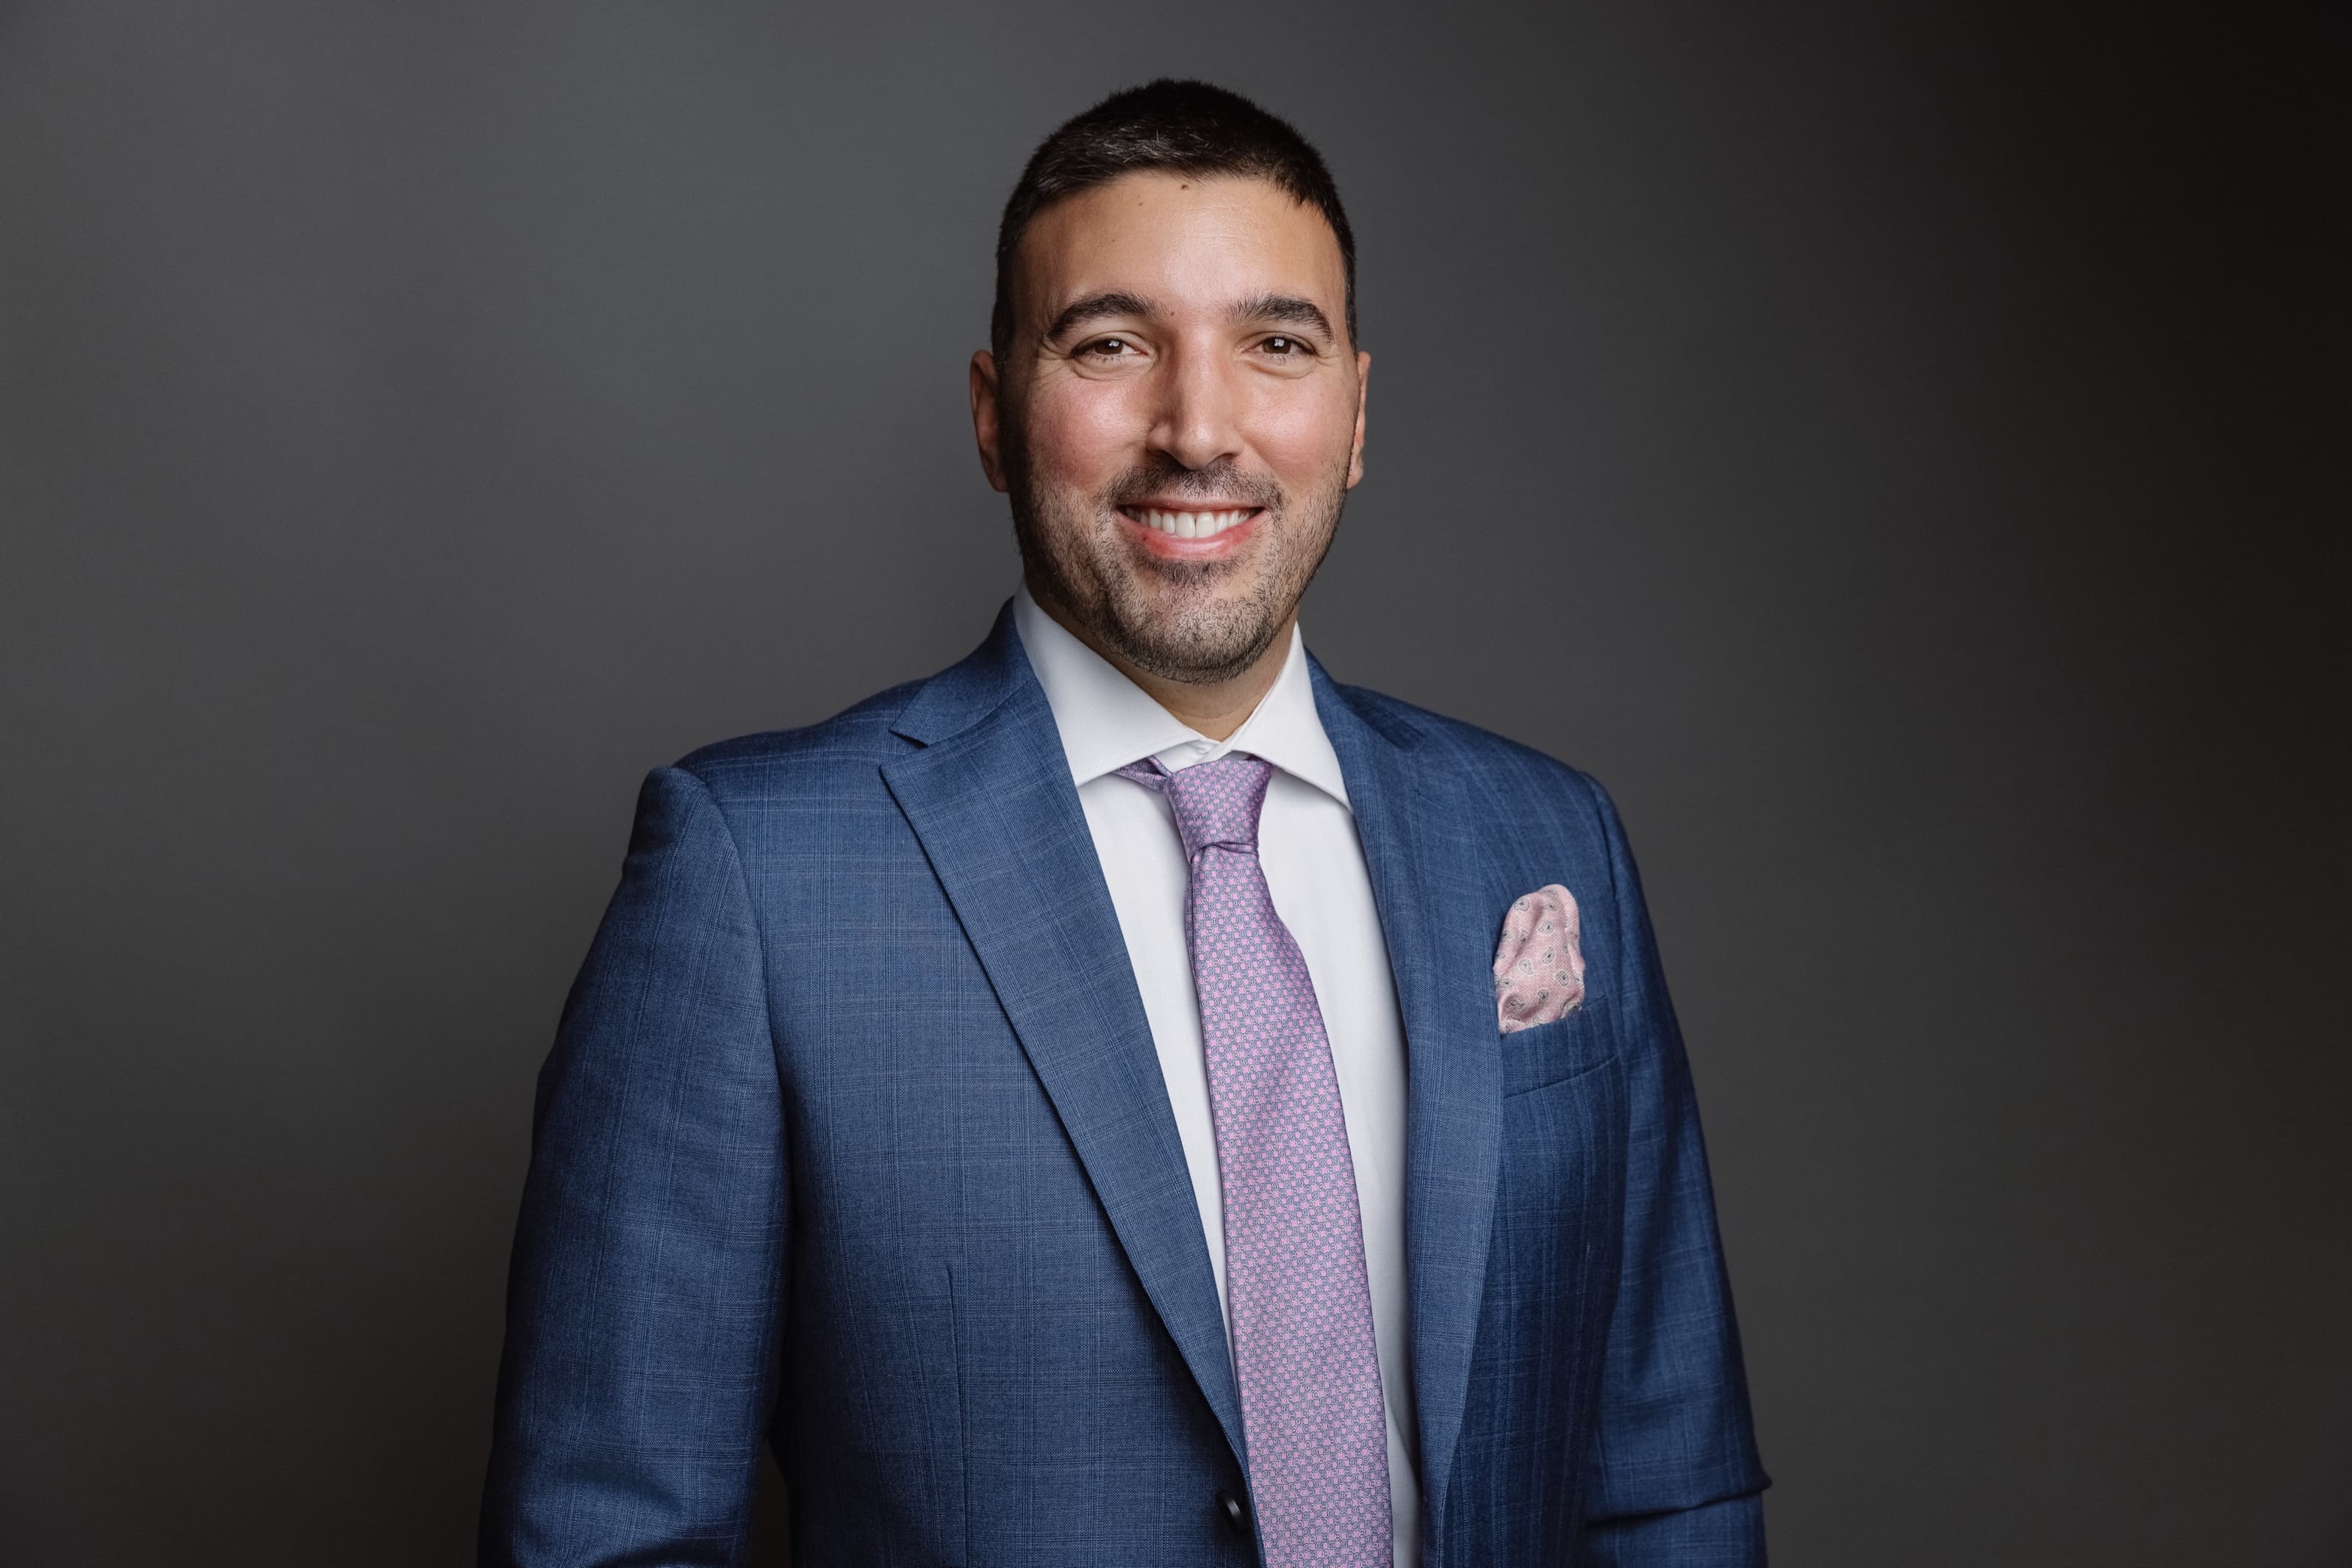
Nathaniel Borg
Audit Director & Co-Founder
Andrew Fenech
Frequently asked questions about Malta corporate tax
What is Malta’s corporate tax rate?
The corporate tax rate in Malta is 35%. Through the shareholder refund system, the overall tax on distributed trading profits is generally 5%. Passive interest and royalties generally come to 10% after the refund, and qualifying holding company income can be exempt.
How does the refund system work?
Malta uses a full imputation system. The company pays 35% tax on its profits, and the tax paid is credited to shareholders when dividends are distributed. The shareholders then claim a refund from the tax authorities. On a trading profit of EUR 100,000, the company pays EUR 35,000 in tax. A 6/7 refund returns EUR 30,000 to the shareholders, leaving EUR 5,000, or 5%.
Is the refund automatic?
No. The shareholder must claim it after a dividend is paid. The refund cannot exceed the tax the company has actually paid on the distributed profits, and the claim must be made within four years of the date the tax becomes eligible for refund. Without a dividend and a complete claim, there is no refund.
Can non-resident shareholders claim the refund?
Yes. Refunds are available to shareholders whether or not they are resident in Malta. Every shareholder who claims must be registered with the tax authorities, so non-resident shareholders register before their first claim.
What is the participation exemption?
A Malta company can be exempt from tax on dividends and capital gains from a participating holding, without a refund claim. The holding must meet the conditions in the Income Tax Act, and further conditions apply to dividends. Groups can combine the exemption and the refund system across different companies.
What about Pillar Two and the global minimum tax?
Pillar Two applies to groups with consolidated revenue of EUR 750 million or more in at least two of the four preceding years. Malta has transposed the EU Minimum Tax Directive and, as Article 50 of the Directive allows, defers applying the income inclusion rule and the undertaxed profits rule for up to six years from 31 December 2023. Groups in scope should review how these rules affect their Malta companies.
What does substance mean for a Malta company?
Substance means genuine economic activity and decision-making in Malta, such as directors who take decisions and board meetings held in Malta. We review what your structure needs.
Can you quote before reviewing our structure?
Fees depend on the companies, the shareholders and the scope, so the first conversation establishes what is involved. Pricing is then agreed in advance in a personalised written proposal, with no hidden charges.
Discuss your Malta tax position
Tell us where things stand and what you would like to discuss.
You will speak with Andrew Fenech